Latest blogs from [Company name].
VAT for Care Recruitment Agencies: Can VAT Be Charged Only on the Agency Margin?
VAT for Care Recruitment Agencies: Can VAT Be Charged only on the Agency Margin?
Recruitment agencies supplying nurses, healthcare assistants and care staff can face particularly complicated VAT rules.
Recurring question is whether VAT should be charged on the whole amount invoiced to the care provider or only on the recruitment agency’s commission or margin.
The First-tier Tribunal case 1stAlternative Medical Staffing Ltd vs HMRC concerned an employment business supplying qualified and unqualified nursing staff and care assistants to NHS and private hospitals and care homes. The company’s charges included employment costs plus a commission. It accounted for VAT on the commission but treated reimbursed employment costs as exempt.
HMRC disagreed. Assessments were initially issued for £265,590 for the relevant periods. The Tribunal ultimately dismissed the company’s appeal on the statutory exemption issue. The case is a useful warning for recruitment companies that separating wages or employment costs from the agency margin does not, by itself, determine the VAT treatment.
VAT on the whole invoice or just the agency margin?
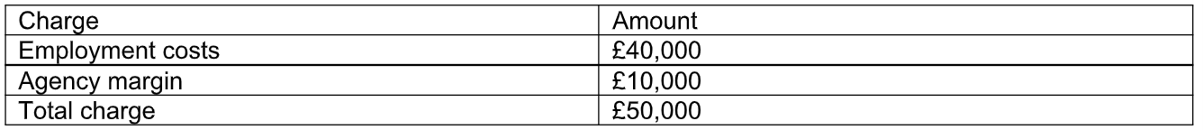
VAT on a £10,000 margin would be £2,000. If, however, the recruitment business is acting as principal and the whole £50,000 is consideration for a standard-rated supply of staff, the VAT would be £10,000. That is an £8,000 difference in one billing period.
Why splitting the invoice does not necessarily solve the VAT issue
Labels such as “reimbursement of wages”, “employment costs” and “agency commission” do not automatically create separate VAT supplies. The contractual and commercial arrangements determine whether the recruitment business is acting as agent or principal and what it is actually supplying.
Where an employment business acts as principal, and supplies workers to a client, VAT can apply to the whole consideration for that taxable staffing supply. Where a business is genuinely acting as an agent, different principles can apply, but agency status needs to be supported by the actual arrangements rather than invoice wording alone.
A recruitment agency is not necessarily supplying healthcare
The fact that the workers themselves provide healthcare does not automatically mean the recruitment company is making an exempt healthcare supply. HMRC’s current guidance says that where a health professional works under the control and guidance of the third-partyclient, the employment business is making a taxable supply of staff. The client is responsible for the healthcare provided to the final patient.
The analysis can differ where the employment business itself retains direction and control of the health professionals and is responsible for providing qualifying medical care directly.
What about the Nursing Agencies’ Concession?
HMRC’s Nursing Agencies’ Concession remains highly relevant to specialist care recruitment businesses. Subject to the conditions, certain direct supplies of nurses, nursing auxiliaries and care assistants can be treated as exempt.
HMRC’s current guidance also confirms that the concession is prospective: it cannot simply be adopted retrospectively for past supplies. It also states that the concession cannot apply where related input tax is recovered in a manner inconsistent with exemption.
For nursing auxiliaries or care assistants, duties must include some direct form of medical care, such as administering drugs or taking blood pressure readings. General personal care alone will not normally be enough.
Why this matters commercially to recruitment agencies
Many customers in the care and healthcare sector have restricted VAT recovery. VAT charged by a recruitment company can therefore become a real cost to the customer. Correct VAT treatment can affect tenders, framework pricing, gross margin and competitiveness.
That makes it important to establish the correct treatment before agreeing fixed charge-out rates or entering significant contracts. Discovering later that VAT should have been charged on a larger value can leave the recruitment company carrying the cost.
Seven VAT questions every care recruitment agency should consider
1. What categories of staff do you supply—registered nurses, healthcare assistants, senior carers, support workers or general care assistants?
2. What duties do those workers actually perform?
3. Who directs and controls the worker while on placement?
4. Is the recruitment company acting as principal or genuinely as agent?
5. Who is responsible for providing the care to the patient or resident?
6. Could the Nursing Agencies’ Concession apply to any category of worker?
7. Are you charging VAT on the correct value and do the contracts and invoices support the treatment?
Starting or growing a care recruitment agency?
VAT can affect more than the VAT return. It can influence:
· charge-out rates and gross margins;
· tenders and framework pricing;
· contracts with care homes and healthcare providers;
· cash flow and working capital;
· VAT registration and input VAT recovery; and
· the competitiveness of the agency’s rates.
How Fairfax Tax & Accounts can help recruitment companies
At Fairfax Tax & Accounts, we work with recruitment businesses, including companies specialising in the supply of staff to the care and healthcare sectors. We aim to support the whole recruitment business rather than looking at VAT in isolation.
· VAT reviews for nurses, healthcare assistants and care staff;
· Aagent versus Principal and invoicing reviews from a tax perspective;
· VAT registration and VAT returns;
· Payroll and PAYE support for recruitment businesses;
· Annual accounts and corporation tax;
· Management accounts, cash-flow and margin reporting;
· Director's remuneration and tax planning; and
· HMRC enquiry and VAT assessment support.
If you operate a recruitment agency supplying nurses, healthcare assistants, carers or other healthcare staff, contact Fairfax Tax & Accounts to discuss your VAT position and the wider accounting, payroll and tax support your agency needs as it grows.