Latest blogs from [Company name].
Do Care Recruitment Agencies Charge VAT? Lessons from the Truth Recruitment Case
The VAT treatment of care agency staff can be a costly area for recruitment businesses. A recent tax tribunal case provides an important reminder that simply supplying workers into the healthcare or care sector does not automatically make the recruitment agency’s supply exempt from VAT.
Truth Recruitment Ltd supplied carers, including senior carers, to nursing and residential care homes. The company argued that its supplies were exempt under the health and welfare provisions in Schedule 9, Group 7 of the VAT Act 1994. HMRC disagreed and treated the company as making taxable supplies of staff. The taxpayer’s appeal was dismissed.
Why does this matter to care recruitment agencies?
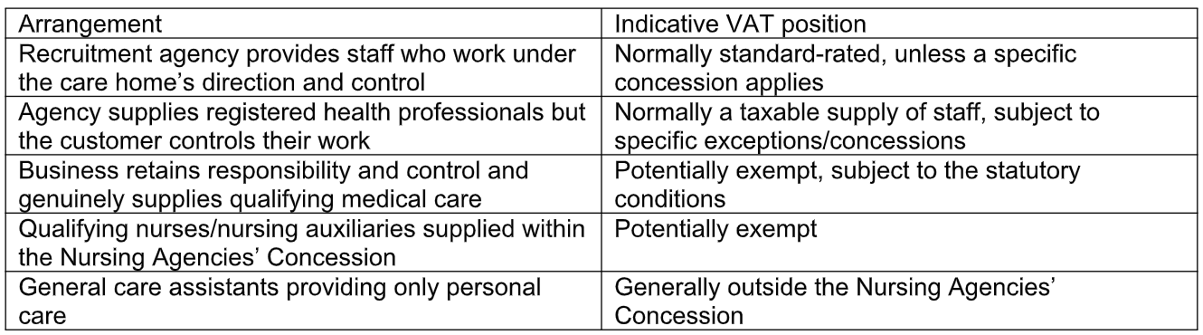
The distinction between supplying care services and supplying staff is crucial. Where an employment business provides workers who then work under the direction and control of a care home or healthcare provider, HMRC will generally regard the recruitment business as making a supply of staff. Supplies of staff are normally subject to VAT at the standard rate, unless a specific exemption or concession applies.
This can have a significant commercial impact because many care and healthcare providers make VAT-exempt supplies and may be unable to recover some or all of the VAT charged by the recruitment agency. A £10,000staffing charge could therefore potentially carry an additional £2,000 of VAT.
What happened in Truth Recruitment Ltd?
The business supplied carers and senior carers to nursing and residential care homes. Importantly, the Tribunal noted that:
· the carers were not qualified medical professionals;
· they were not supervised by qualified medical professionals;
· there was no evidence that the recruitment company itself was supplying medical care; and
· the business was effectively providing staffing solutions to care homes.
Although the carers undertook duties which included administering medication, that did not establish that the recruitment company itself was making an exempt supply of healthcare. On the evidence before it, the Tribunal found no basis for the claimed exemption.
Administering medication does not automatically make the agency’s supply exempt
A key VAT question is not simply what an individual worker does during a shift, but what the recruitment business is supplying to its customer. If the care home decides which residents the worker looks after, determines their duties and working patterns, and supervises the worker, the underlying supply by the agency may still be a taxable supply of staff.
HMRC’s current Notice 701/57 states that where an employment business supplies health professionals who work under the control and guidance of the customer, the employment business is generally supplying staff rather than healthcare. The position can differ where the employment business retains direction and control and is itself responsible for delivering qualifying medical care.
What about the Nursing Agencies’ Concession?
Care recruitment businesses should not assume that every supply of care staff is standard-rated. HMRC operates an extra-statutory concession commonly known as the Nursing Agencies’ Concession. Subject to its conditions, qualifying supplies of nurses, nursing auxiliaries and certain care assistants can be treated as exempt.
For nursing auxiliaries or care assistants, HMRC’s guidance requires duties to include a direct form of medical care, such as administering drugs or taking blood pressure readings. General care assistants who only provide personal care such as washing, dressing or catering will not normally fall within the concession. The precise customer, setting, duties and other conditions therefore matter.
Supply of staff versus supply of care services
Why getting the VAT treatment wrong can be expensive
If a recruitment agency incorrectly treats taxable staffing supplies as exempt, HMRC may assess the business for VAT that should have been charged. Recovering that VAT from historic customers may be commercially difficult, particularly where the customer cannot recover the VAT itself.
The opposite problem also matters. An agency that charges VAT where a valid exemption or concession applies may make its rates less competitive. VAT therefore affects compliance, pricing, margins, tenders and cash flow.
Five VAT questions for care recruitment agencies
What staff do you supply? Registered nurses, healthcare assistants, senior carers, support workers and general care assistants can raise different VAT issues.
What duties do they actually perform? Medical or nursing-related duties can be important when considering the Nursing Agencies’Concession.
Who directs and controls the worker? Client control is an important indicator that the agency is supplying staff.
Whose responsible for the patient or resident’s care? Supplying personnel is different from being contracted to provide the underlying care service.
Do your contracts and invoices match the commercial reality? Contract wording alone will not determine the VAT treatment if what happens in practice is different.
How Fairfax Tax & Accounts can help care recruitment businesses
At Fairfax Tax & Accounts, we work with recruitment companies, including businesses specialising in care and healthcare staff. We can review the VAT position as part of the wider financial and tax needs of the recruitment business.
· reviewing the VAT treatment of nurses, carers and healthcare assistants;
· assessing whether the Nursing Agencies’ Concession could apply;
· VAT registration and VAT return support;
· reviewing contracts and invoicing arrangements from a tax perspective;
· PAYE and payroll support;
· annual accounts and corporation tax;
· management accounts, margins and cash-flow reporting; and
· support with HMRC enquiries and VAT assessments.
If you run a recruitment agency supplying nurses, healthcare assistants, carers or other healthcare staff, speak to Fairfax Tax &Accounts about reviewing your VAT position and supporting the wider accounting, payroll and tax needs of your agency.